Your down payment back, plus additional cash from your equity
The BRRRR gets your down payment back. The SUPER BRRRR is built to return your down payment plus additional cash from your bought and forced equity, with no seasoning on the ARV, so every deal funds a bigger one.
BRRRR gets your down payment back. SUPER BRRRR pays you more.
The BRRRR gets your down payment back. The SUPER BRRRR is built to return your down payment plus additional cash from the equity you bought and forced, as soon as the rehab is done, so you scale into bigger properties without hunting for the next down payment.
The 5 levers that make it SUPER
The secret: leverage + no seasoning + the appraisal
Your cash-out is only as big as your appraisal
Leverage gets you in with 10% down. No seasoning on the ARV gets your money out the moment the work is done. And the appraisal decides how much comes back. Our proprietary process prepares the comps, a detailed scope of work and the rehab documentation before the appraiser walks in, so your value reflects every dollar of work you did.
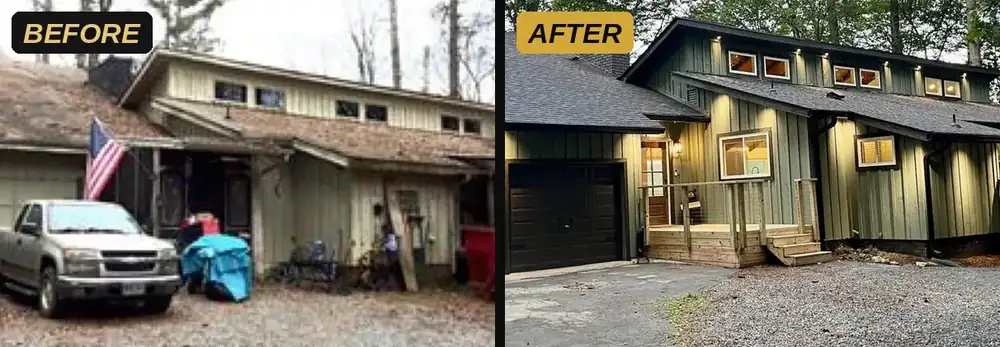
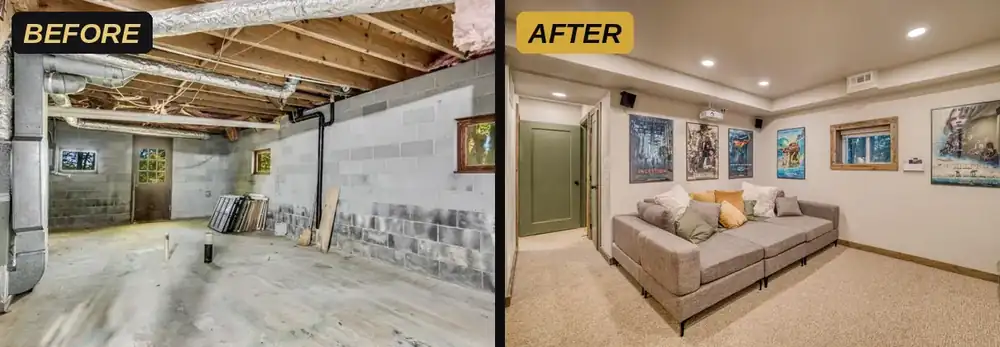
From a real scope of work: this is the documentation the appraiser sees.
If you want The Appraisal Advantage, get it here.
Real deal: Kelseyville, CA
Marina View Dr: hard money to DSCR
Single-family rental · purchased Oct 2025 · refinanced Oct 2026
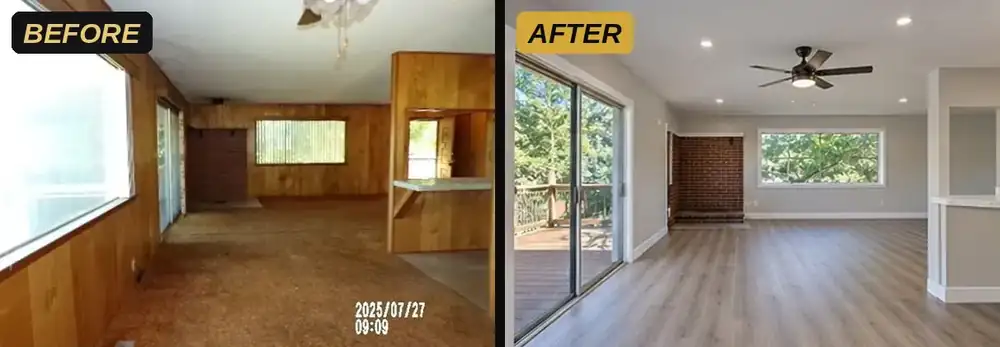
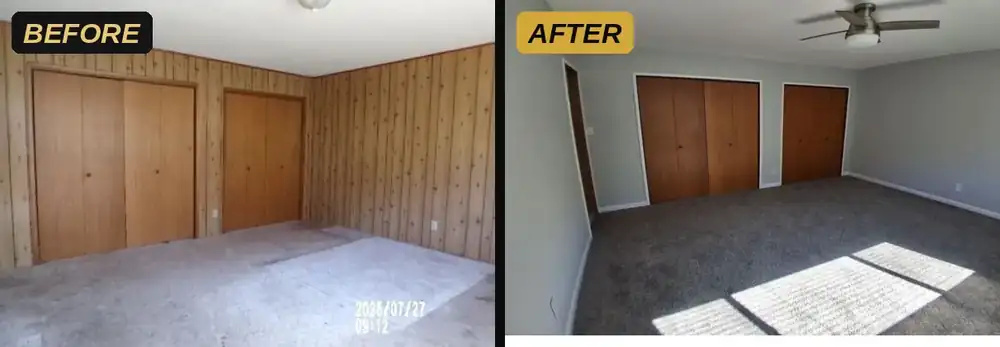
Buy: $180K purchase with $18K down (10%) on a hard money loan, with the $35K renovation and the closing costs financed.
Refinance: no-seasoning DSCR cash-out at 80% of the $339K ARV: $271,200. After paying off the hard money loan, about $58K came back to the investor.
The result: the $18K down payment back, plus about $40K in cash from bought and forced equity, ready for a bigger down payment on the next deal.
How it compounds
Real estate pays you four ways, and every one of them grows with the size of the asset:
The SUPER BRRRR vs. a classic BRRRR
| SUPER BRRRR | Classic BRRRR | |
|---|---|---|
| What you get back | Your initial down payment plus cash from your forced equity | Your initial capital, hopefully |
| Buying | A lower MAO puts bought equity into your cash-out refi after the renovation: more money back to you | Equity from the rehab only |
| Closing costs | Strategic closing negotiations get you your price and seller concessions for your costs. Ask us how. | Paid out of pocket |
| Refinance | No seasoning on the ARV | Often a seasoning wait before the ARV counts |
| Rents | Actual rents: more rent, a bigger loan, more cash | 1007 market rents from the appraiser |
| Appraisal | The Appraisal Advantage, built for maximum value | A standard appraisal |
| The next deal | Cash-out beyond your initial investment buys you bigger deals | You get just your initial capital back, hopefully |
How it works, step by step
- Find and negotiateBuy at your MAO and negotiate seller concessions toward your closing costs.
- Buy with the right hard money loan10% down, with the rehab and your closing costs financed.
- RenovateForce the value. Your draws fund the work, and every improvement is documented for the appraisal.
- Rent itLong-term, mid-term or short-term. More rent supports a bigger loan and more cash out.
- Refinance on the full ARVNo-seasoning DSCR cash-out up to 80% pays off the hard money and returns your down payment plus your equity in cash.
- ScaleUse the cash-out as a bigger down payment on a bigger deal. Repeat.
Questions investors ask
What is the SUPER BRRRR?
The DSCR Kings version of the BRRRR strategy. A classic BRRRR aims to get your initial capital back. The SUPER BRRRR aims to return your initial down payment plus cash from your bought and forced equity, by negotiating a lower MAO and seller concessions, financing the purchase and rehab with hard money, and refinancing on the full ARV with no seasoning.
How do you get higher appraisals?
Through our proprietary appraisal process, The Appraisal Advantage: comps, a detailed scope of work and rehab documentation prepared before the appraiser arrives.
How much do I need to bring to buy?
As little as 10% down on qualified hard money purchases, with the renovation and your closing costs financed. Leverage depends on the deal, your credit and your experience.
Do I have to wait 6–12 months to refinance?
No. Our DSCR refinances have no seasoning requirement, so you can refinance as soon as the work is complete.
Is the refinance based on what I paid or on the ARV?
On approved loans, the cash-out can be based on the full ARV from the new appraisal, up to 80% LTV, rather than your purchase price plus rehab.
Can I do this in an LLC?
Yes. Both loans close in your LLC or other entity, and business-purpose loans in an entity typically don’t report to your personal credit.
Get your terms
Send the deal. We’ll structure it to qualify for the best terms our capital partners offer, and show you the options side by side.
Business-purpose loans for investment properties only; not for owner-occupied homes. Terms, leverage and approval depend on the property, the borrower’s credit and capital-partner guidelines and are not guaranteed. Programs and availability vary by state. Where state law requires a license, loans are originated through appropriately licensed partners.